

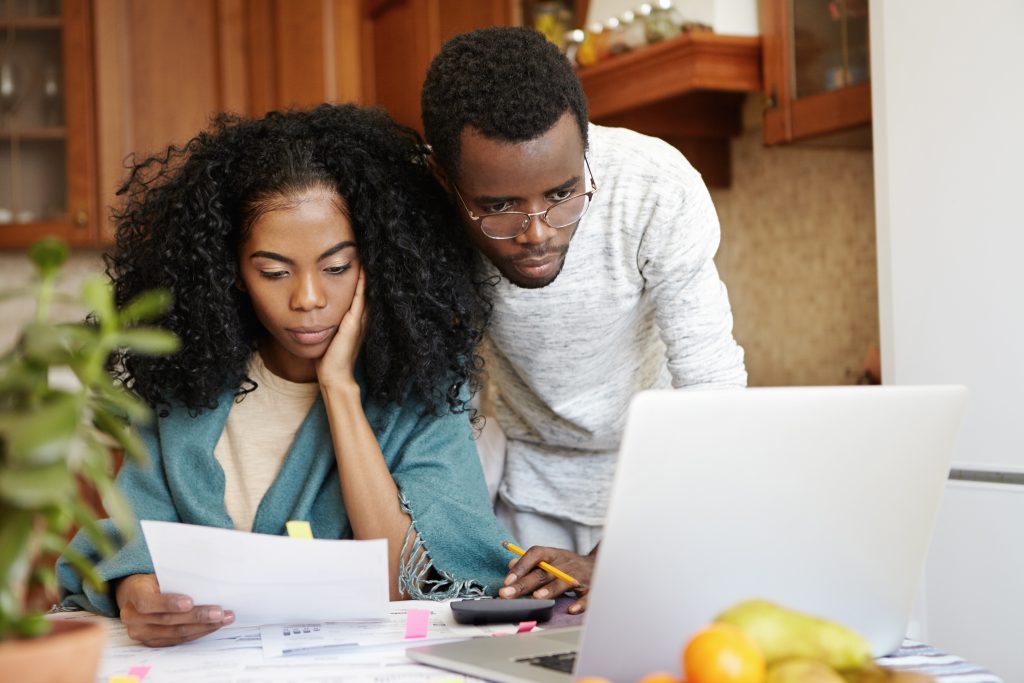
For many American households, the final months of the year bring a difficult financial combination. Christmas gifts, family gatherings, travel plans, and seasonal shopping arrive just as colder temperatures increase heating and electricity expenses. Even families that normally manage their money carefully can struggle when several large bills become due within a short period. Without preparation, these overlapping costs can lead to missed payments, overdraft fees, or growing credit card balances.
The solution isn’t necessarily canceling every celebration or turning off the heat to save money. It’s understanding which expenses are unavoidable, identifying where spending can be adjusted, and organizing payments before they create a cash flow problem. A realistic winter budget can help protect essential services while leaving room for meaningful seasonal activities.
Why Winter Can Make Your Regular Budget Unreliable
A household budget that works comfortably during spring or summer may become insufficient when temperatures fall. Heating systems often run longer, electricity consumption may increase, and some families face additional expenses for winter clothing, vehicle maintenance, and home repairs. These changes can be particularly challenging when income remains the same but essential household costs rise.
Consider a family whose regular monthly expenses total $3,800 against take-home income of $4,500. That leaves $700 for savings, discretionary purchases, and unexpected costs. If heating expenses rise by $180 and seasonal activities add another $400, the household has only $120 of its original flexibility remaining. A single car repair or medical bill could eliminate that margin entirely. Recognizing this pressure early makes it easier to adjust spending before financial problems develop.
Put Essential Bills Ahead of Seasonal Purchases
When money becomes tight, the order in which you pay expenses matters. Housing, utilities, groceries, transportation needed for work, insurance, and required debt payments should generally take priority over optional shopping and entertainment. Missing an essential payment can create consequences that extend beyond a single billing cycle, including late fees, service interruptions, and additional financial stress.
Create a payment calendar showing each bill’s due date, expected amount, and the paycheck that will cover it. If several major expenses fall during the same week, contact providers before the due dates to ask about available payment arrangements. Some companies may offer different billing dates or assistance programs, although eligibility and availability vary. Planning around your actual pay schedule is more reliable than assuming your account balance will cover everything when payments arrive.
Estimate Heating Costs Before the Coldest Months
One of the most useful budgeting steps is reviewing your utility bills from the previous winter. Look at the amounts charged during your coldest months and compare them with your current payments. Although weather conditions, energy prices, and household usage can change, past statements provide a more realistic starting point than relying exclusively on your most recent bill.
If your electricity and heating costs averaged $160 during warmer months but reached $290 during winter, you could plan for an additional $130 monthly expense. Setting aside money before those increases arrive helps reduce the impact on your checking account. Households using natural gas, electricity, heating oil, or propane should also account for differences in billing and delivery schedules, particularly when fuel purchases require larger payments at once.
Reduce Heating Expenses Without Sacrificing Safety
Small improvements in household energy efficiency can help reduce unnecessary consumption. Sealing drafts around windows and doors, replacing dirty HVAC filters according to manufacturer recommendations, and using a programmable thermostat appropriately may lower heating demand. Keeping furniture away from vents and maintaining heating equipment can also improve system performance, although actual savings depend on your home, climate, and equipment.
Avoid extreme measures that could create health or safety risks. Never use outdoor grills, gas ovens, or generators to heat indoor spaces because they can cause dangerous carbon monoxide exposure. Space heaters should be operated according to manufacturer instructions and kept away from flammable materials. If your heating system is malfunctioning, addressing the problem promptly may prevent larger repair costs while helping maintain a safe indoor temperature.
Check Whether Your Utility Company Offers Budget Billing
Some utility providers offer budget billing programs that spread estimated annual energy costs across more consistent monthly payments. Instead of paying much higher bills during winter and lower amounts during milder seasons, participating customers may receive more predictable charges throughout the year. This can make household budgeting easier, especially for families whose income doesn’t fluctuate with the seasons.
However, budget billing doesn’t necessarily reduce the total amount of energy you consume or the overall cost of service. Providers may periodically adjust payments based on actual usage, and some programs include reconciliation balances. Before enrolling, ask how monthly amounts are calculated, when adjustments occur, and what happens if you leave the program. Predictable payments can be useful, but understanding the conditions helps prevent an unexpected balance later.
Look for Financial Assistance Before Bills Become Overdue
Households struggling with heating expenses may qualify for assistance through government-supported or local programs. In the United States, the Low Income Home Energy Assistance Program, commonly known as LIHEAP, helps eligible households with certain home energy costs. Funding, eligibility requirements, application periods, and available benefits differ by state and local administering agency.
You can begin by contacting your state’s LIHEAP office, local community action agency, or utility provider to ask about available support. Some providers also offer hardship programs, payment plans, or referrals to nonprofit organizations. Applying early is important because assistance may be limited and processing can take time. If you receive a disconnection notice, contact the utility immediately to understand your options and any protections that may apply in your state.
Set a Seasonal Spending Limit Based on What’s Left
Your Christmas and New Year’s budget should reflect the money remaining after essential winter expenses are accounted for, not the amount you would like to spend. Start with expected take-home income, subtract regular bills and higher seasonal utility costs, and reserve money for necessary savings or upcoming obligations. The remaining amount can help determine a reasonable limit for gifts, travel, meals, and entertainment.
Suppose your household has $500 available for seasonal activities after covering essential expenses. You might allocate $250 for gifts, $150 for family meals, and $100 for entertainment. If those limits feel restrictive, adjust the celebration rather than automatically borrowing the difference. Organizing a gift exchange, hosting a potluck dinner, or choosing free local activities can reduce spending without eliminating the social experiences that make the season meaningful.
Avoid Using Credit Cards to Cover Every Shortfall
Credit cards can provide payment flexibility, but using them repeatedly to cover utility bills and seasonal purchases may create expensive balances. Some utility companies also charge convenience fees for card payments, increasing the total cost. When interest begins accumulating on unpaid balances, the financial impact of one difficult month can extend well into the following year.
If you’re considering using a credit card because your checking account is short, first review whether a payment arrangement, spending reduction, or available assistance program could address the problem. If you must borrow, understand the interest rate, fees, and repayment schedule before committing. Prioritize a plan that prevents essential services from being interrupted while minimizing additional costs. Borrowing should not become the default solution for expenses that predictably return every winter.
Build a Winter Expense Fund for Next Year
Once the busiest spending period ends, use what you’ve learned to prepare for the next one. Add up the extra amount you spent on heating, winter-related necessities, gifts, and celebrations. Then divide that total into manageable monthly savings contributions. This turns a concentrated seasonal expense into something you can prepare for gradually throughout the year.
For example, if winter utilities and seasonal activities create $1,800 in additional annual expenses, saving $150 monthly would accumulate that amount over twelve months, assuming you begin with no balance and make every contribution. Keep the money in an accessible savings account and review the target when prices or household circumstances change. Building this reserve can reduce the need to depend on credit cards when the next winter arrives.
Keep Your Home Comfortable and Your Finances Under Control
Managing winter expenses requires balancing immediate household needs with seasonal priorities. Higher utility bills are often unavoidable, but unnecessary energy consumption, unplanned shopping, and poorly timed payments can make the financial pressure worse. Reviewing previous bills, planning around paycheck dates, and exploring available assistance can help households maintain essential services without sacrificing their entire budget.
The most effective approach is to prepare for winter as a predictable annual expense rather than an unexpected emergency. Protect essential payments first, set realistic limits for celebrations, and build a dedicated reserve for future costs. With these habits, you can keep your home comfortable, enjoy time with family, and enter the new year with greater financial stability.
 Are Store Credit Cards Worth It? Hidden Costs and Benefits You Should Know <p class='sec-title' style='line-height: normal; font-weight: normal;font-size: 16px !important; text-align: left;margin-top: 8px;margin-bottom: 0px !important;'> Are store credit cards worth it? Explore hidden fees, high interest rates, rewards, and when opening a store card makes financial sense. </p>
 How to Spot Fake Discounts and Avoid Impulse Buying When Shopping Online <p class='sec-title' style='line-height: normal; font-weight: normal;font-size: 16px !important; text-align: left;margin-top: 8px;margin-bottom: 0px !important;'> Learn how to spot fake online discounts, recognize misleading sales tactics, avoid impulse buying, and protect your budget. </p>
 How to Split Household Expenses Fairly When Living With Family or Roommates <p class='sec-title' style='line-height: normal; font-weight: normal;font-size: 16px !important; text-align: left;margin-top: 8px;margin-bottom: 0px !important;'> Learn how to split rent, utilities, groceries, and household expenses fairly with roommates or family while avoiding money and late payments. </p>